Tesla delivery performance vs analyst forecasts
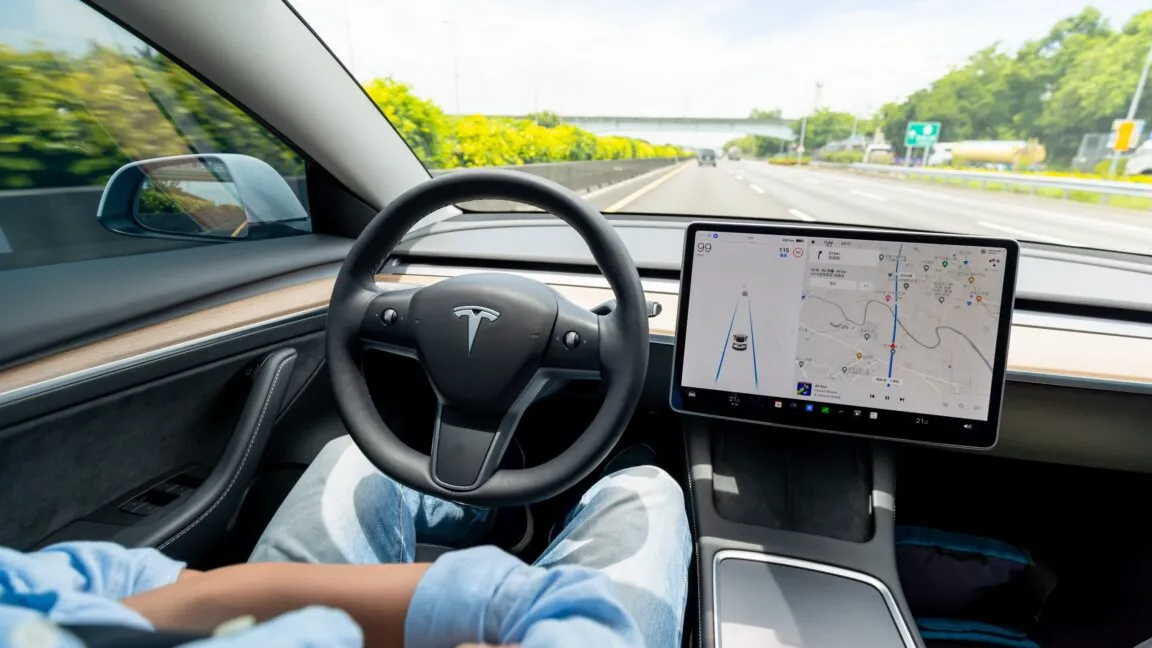
Tesla delivered 486,532 electric vehicles during the third quarter of 2026, marking a slight contraction compared to the previous year. According to Ars Technica, this represents a 2.1 percent decrease from the 497,099 units sold during the same period in 2025. While a downward trend might typically alarm investors looking for exponential growth, the actual results provided a sense of relief to the market.
The primary reason for the positive stock reaction following the announcement was the company's ability to beat consensus estimates. Analysts had projected a much steeper decline of approximately 8 percent, with expectations set at 456,600 cars. By delivering over 486,000 units, Tesla demonstrated a level of resilience that exceeded the more bearish outlooks held by many financial experts.
Market reaction to delivery data
Despite the year-over-year decline, the stock price responded favorably to the news. This suggests that the market had already priced in a significant slowdown, and Tesla's ability to mitigate that drop was viewed as a win. The gap between the 2.1 percent actual decline and the 8 percent predicted decline highlights the importance of managing investor expectations in a volatile EV market.
Production trends and Model 3/Y dominance
Total vehicle production at Tesla actually showed an upward trajectory, contrasting with the slight dip in total deliveries. According to Ars Technica, the company built 464,391 vehicles in Q3 2026, which constitutes a 3.7 percent increase compared to the third quarter of 2025. This indicates that Tesla is maintaining or even expanding its manufacturing capacity even as sales growth fluctuates.
The vast majority of this production is concentrated in the company's most popular segments. Specifically, Model 3 and Model Y production reached 457,387 units, representing a 4.9 percent year-over-year increase. These two models remain the backbone of Tesla's operational volume, providing the necessary scale to support the company's global footprint.
The shift in model composition
As the Model S and Model X lines have effectively been retired from primary production status, the manufacturing mix has shifted heavily toward the mass-market platforms. This concentration allows for greater efficiency but also makes the company's overall performance highly sensitive to the demand cycles of just two specific vehicle types.
Challenges in non-core model sales
While the core lineup remains stable, Tesla faced significant headwinds in its secondary vehicle categories. The sales for "other models" experienced a severe downturn, dropping by 48 percent to a total of 8,295 units. This category includes newer and more specialized entries such as the Cybertruck, and potentially some Semi or Cybercab units.
The decline in this segment is particularly striking when compared to the growth in the Model 3 and Y lines. According to Ars Technica, the 7,004 units produced in this category—which mostly consist of Cybertrucks—did not translate into the high sales volume some had anticipated. This discrepancy between production and sales in the niche category suggests that Tesla is currently facing a mismatch between its specialized vehicle output and consumer adoption rates.
Cybertruck and specialized vehicle outlook
The volatility in the "other" category highlights the difficulty of scaling unconventional vehicle designs. While the Cybertruck remains a high-profile part of the fleet, the data suggests that it has not yet achieved the consistent sales velocity required to offset the decline in older or more specialized model segments.
Growth in Tesla energy storage deployment
One of the most positive takeaways from the Q3 2026 report was the robust performance of Tesla's energy division. While the automotive sector faced a slight contraction, the energy storage business showed significant momentum. According to Ars Technica, Tesla deployed 13.7 GWh of energy storage products between July and September 2026.
This deployment represents a 9.6 percent increase year-over-year, providing a vital secondary revenue stream that helps diversify the company's profile. As the global transition to renewable energy continues, the ability to scale energy storage solutions may become as critical to Tesla's valuation as its automotive manufacturing capabilities.
Diversification as a hedge
The growth in energy storage acts as a strategic hedge against the cyclical nature of the automotive market. By expanding into utility-scale and residential energy solutions, Tesla is positioning itself as a broader energy technology company rather than a pure-play automaker, which may offer more stability in future quarters.
Frequently Asked Questions
How many EVs did Tesla sell in Q3 2026?
Tesla sold 486,532 electric vehicles during the third quarter of 2026. This figure represents a 2.1 percent decrease compared to the 497,099 vehicles the company delivered during the same quarter in 2025, though it still surpassed analyst expectations.
Did Tesla's production increase in 2026?
Yes, Tesla's total production increased year-over-year during the third quarter. The company manufactured 464,391 vehicles, which is a 3.7 percent increase over the production levels recorded in Q3 2025, driven largely by the Model 3 and Model Y lines.
What happened to Tesla's energy storage business?
The energy storage business saw significant growth during the third quarter of 2026. Tesla deployed 13.7 GWh of energy storage products, marking a 9.6 percent increase compared to the same period in the previous year, showing strength outside of the automotive sector.
Final assessment of Tesla's quarterly performance
The Q3 2026 results present a picture of a company in transition. While the 2.1 percent decline in vehicle deliveries and the sharp drop in non-core model sales indicate cooling demand for certain segments, Tesla's ability to outperform analyst forecasts and grow its energy storage business provides a stabilizing narrative. The company is successfully leveraging its mass-market Model 3 and Y production to maintain scale, even as it navigates the complexities of introducing newer models like the Cybertruck. Investors will likely look toward the upcoming financial results on October 21 to see how these operational shifts translate into bottom-line profitability.